Kotak Mahindra Bank Q2 profit jumps 29% to ₹4,212cr as loans grow 25%
Kotak's Q2 profit rose 29% to ₹4,212cr and loans 25%, but ₹55,344cr of FCNR(B) dollar deposits cut its margin to 4.31%. What CFOs and boards need to know.
Pulled from WCRC Leaders. Original publication date and full article text retained. Source category: Latest Insights.
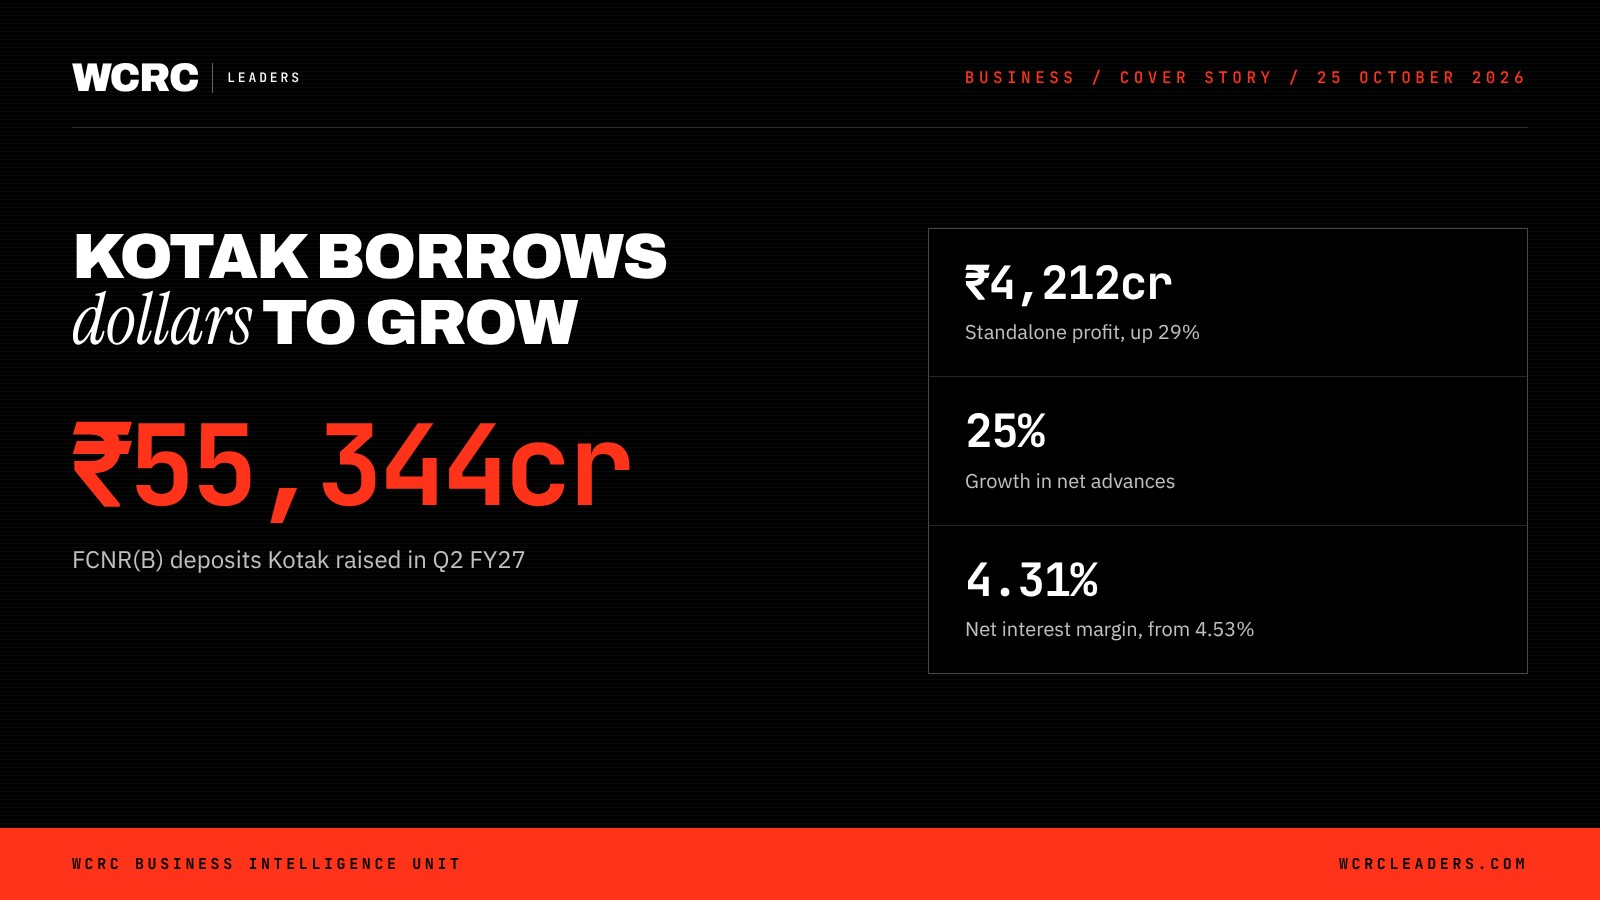
At a glance: WCRC Leaders' assessment: Kotak has turned the RBI's dollar window into balance-sheet growth at a modest cost to margin, and borrowing companies should read its results as a sign that bank funding is plentiful now but will not stay cheap. On 24 October Kotak Mahindra Bank reported standalone profit of ₹4,212 crore for the quarter to 30 September 2026, up 29%. Net advances rose 25% and deposits 23%, helped by about ₹55,344 crore of FCNR(B) deposits. Net interest margin fell to 4.31% from 4.53% in the June quarter.
What did Kotak report?
Kotak Mahindra Bank, one of WCRC 1000, India's Most Valuable Enterprises 2026, posted standalone profit after tax of ₹4,212 crore for the second quarter of FY27, against ₹3,253 crore a year earlier and ₹4,123 crore in the June quarter. Consolidated profit, which takes in the securities, asset management, life insurance and vehicle finance arms, rose 26% to ₹5,645 crore.
The headline growth rests on three things. Net interest income rose 16% to ₹8,459 crore. Fees and services rose 21% to ₹2,926 crore. And credit costs fell sharply: provisions dropped 15% to ₹803 crore, and the annualised credit cost came down to 0.35% from 0.79% a year ago. Slippages fell 24% to ₹1,230 crore.
Asset quality improved on every measure the bank publishes. Gross NPAs were 1.04% of loans, against 1.39% a year earlier. Net NPAs were 0.24%, down from 0.32%, and the provision coverage ratio was 78%. Operating costs rose 14%, slower than income, and cost to assets fell to 2.40% from 2.67%. Return on assets was 1.92% on a standalone basis, and capital remained ample, with a CET1 ratio of 21.4%.
On the balance sheet, net advances reached ₹5,77,295 crore, up 25%. Total deposits stood at ₹6,51,491 crore, up 23%.
Why is a rupee bank raising dollars?
The bank's release is direct about where the extra growth came from. During the quarter Kotak "mobilised FCNR(B) deposits aggregating to ~₹55,344 crore and provided loans aggregating to ~₹16,110 crore" through its international branches. Strip the FCNR(B) money out and deposits grew 13%, not 23%. Strip out FCNR(B)-linked loans and the KMIL portfolio, and advances grew 19%, not 25%.
FCNR(B) deposits are foreign currency term deposits held by non-resident Indians. Banks raised them in volume because of a special facility the Reserve Bank of India opened on 8 June 2026. Under that circular, banks could swap fresh FCNR(B) deposits of three to five years with the RBI, buying and selling dollars at the same FBIL reference rate on both legs. In effect, the central bank took the currency risk and the hedging cost off the banks' hands. Deposits carry a one-year lock-in, and completed swaps cannot be cancelled.
The response was enormous. RBI data show FCNR(B) inflows of $65.4bn by 21 August. The RBI then closed the FCNR(B) leg on 31 August, a month before the 30 September end date in the original circular, and the final tally reported by banks reached $132.98bn. Total swap inflows, including external commercial borrowings and overseas foreign currency borrowings, came to $143.6bn by 18 September. The ECB and OFCB window stays open until 31 December 2026. WCRC has set out what that rupee defence is costing India's biggest banks.
For Kotak, the logic is simple. Dollars swapped with the RBI become rupee liquidity at a known cost, which the bank can lend at home. That helps explain how advances could grow faster than deposits excluding FCNR(B), and why the credit-to-deposit ratio rose to 88.6% from 87.5% a year earlier.
Why did the margin fall?
Net interest margin fell to 4.31%, from 4.54% a year earlier and 4.53% in the June quarter. The bank attributed this "largely" to FCNR(B) mobilisation. Its cost of funds edged up to 4.52% from 4.46% in the June quarter, though it remains below the 4.70% of a year ago.
WCRC analysis: two effects are at work. First, about ₹55,000 crore of term money arrived in one quarter, and a large pool of fresh funds takes time to deploy at full yield. Second, RBI rules allow banks to lend to FCNR(B) depositors against a lien on their deposits. Such secured loans earn a thin spread. Kotak's release does not describe the ₹16,110 crore of international loans in detail, but loans of this kind add assets and interest income while lowering the margin ratio. The FCNR(B) money also pushed the CASA ratio down to 38.2% from 42.3%; excluding FCNR(B), it was 41.8%.
The trade-off was clearly worth it to the bank. Net interest income still grew 7% on the quarter. At 4.31%, the margin remains well above HDFC Bank's 3.16%.
How does it compare with HDFC Bank?
HDFC Bank, one of WCRC 1000, India's Most Valuable Enterprises 2026, reported its quarter on 17 October. Its standalone profit rose 4.7% to ₹19,510 crore, net interest income rose 9.7% to ₹34,620 crore, and its margin was 3.16% on total assets. End-period deposits grew 18.8% and gross advances 16.3%. Gross NPAs were 1.11% and the CASA ratio 32%.
HDFC Bank also used the window. Its retail assets include ₹54,800 crore of FCNR leverage loans; excluding them, retail asset growth was 9.1% year on year. WCRC's analysis of HDFC Bank's quarter found deposits finally outrunning loans as the bank prepares for a new chief executive.
The contrast is instructive. HDFC Bank's FCNR leverage book is more than three times the ₹16,110 crore Kotak lent through its international branches, though Kotak's balance sheet is far smaller. Kotak lent out about 29% of the FCNR(B) money it raised and kept the rest as rupee funding. WCRC analysis: HDFC Bank leaned on the window to support retail lending growth. Kotak used it to accelerate lending from a healthier starting point, with a higher margin, a lower loan-to-deposit ratio and a stronger CASA base.
Who will run the bank next?
Kotak's leadership is about to change. On 1 October the bank announced that the RBI had approved Anup Kumar Saha as managing director and chief executive for three years from 1 January 2027. Ashok Vaswani remains MD and CEO until then. Saha joined Kotak in January 2026 as a whole-time director and has overseen the retail bank, data analytics and marketing since March. He was previously managing director and chief executive of Bajaj Finance, one of WCRC 1000, India's Most Valuable Enterprises 2026.
"We will remain firmly focused on doing the right thing and getting it right by the customer," Saha said in the bank's announcement. He inherits a bank growing loans at 25% with capital to spare, and a funding base that will need re-pricing once the FCNR(B) lock-ins expire between June and August 2027.
Kotak Mahindra Bank is a WCRC MegaBrand in private and wealth banking and was named among India's Most Loved 250 Workplaces 2026 by WCRC.
What should borrowing companies take from this?
The money banks raised in June to August is now on their balance sheets, and they need to lend it. That favours borrowers with strong credit in the near term. But the price of money is rising. On 7 October the RBI's Monetary Policy Committee raised the repo rate by 25 basis points to 5.50% and moved its stance to calibrated tightening, saying rate cuts are "off the table in the near term". WCRC has looked at what that first hike since 2023 means for capex.
For CFOs in India, the open ECB and OFCB swap window, which lets proceeds be swapped with the RBI through banks for a tenor matched to repayment, is worth costing before it shuts on 31 December. For Gulf and Asian lenders and treasuries, the FCNR(B) surge shows how quickly the Indian diaspora's savings, much of it held in the Gulf, can be drawn home when the RBI removes the currency risk.
The WCRC View
The WCRC Business Intelligence Unit reads Kotak's quarter as a well-executed use of a policy window, not a change in the bank's character. Profit growth of 29% owes much to lower credit costs and fee growth, and the dollar money added scale at the cost of about 22 basis points of margin.
Who gains: Kotak gains loan share and liquidity, and its depositors earn a dollar return with the currency risk sitting with the RBI. Corporate borrowers gain a period of easy bank credit. The RBI carries the bill when the swaps mature, mostly between 2029 and 2031.
What leaders should do now: lock in term funding from banks while their balance sheets are flush, and test any ECB plan against the swap window's 31 December deadline. Boards should not assume today's loan pricing survives a tightening cycle.
What WCRC will watch: whether Kotak's margin recovers in the December quarter as funds are deployed, how deposits behave when lock-ins lapse in mid-2027, and what strategy Anup Kumar Saha sets out after 1 January 2027.
Quick answers
Q: How much did Kotak Mahindra Bank earn in Q2 FY27? A: Standalone profit was ₹4,212 crore, up 29% year on year. Consolidated profit was ₹5,645 crore, up 26%.
Q: Why did Kotak's net interest margin fall? A: The bank said the fall to 4.31% from 4.53% in the June quarter was largely due to FCNR(B) deposit mobilisation of about ₹55,344 crore.
Q: What is the RBI's FCNR(B) swap facility? A: Opened on 8 June 2026, it let banks swap fresh three- to five-year FCNR(B) deposits with the RBI at the same rate on both legs. The FCNR(B) leg closed on 31 August after $132.98bn of inflows.
Q: Who will be Kotak Mahindra Bank's next CEO? A: The RBI has approved Anup Kumar Saha as MD and CEO for three years from 1 January 2027. Ashok Vaswani is MD and CEO until then.
Questions about this story
These answers summarise the article and refer to its original reporting period.
What did Kotak report?
Asset quality improved on every measure the bank publishes. Gross NPAs were 1.04% of loans, against 1.39% a year earlier. Net NPAs were 0.24%, down from 0.32%, and the provision coverage ratio was 78%. Operating costs rose 14%, slower than income, and cost to assets fell to 2.40% from 2.67%. Return on assets was 1.92% on a standalone basis, and capital remained ample, with a CET1 ratio of 21.4%.
Why is a rupee bank raising dollars?
The bank's release is direct about where the extra growth came from. During the quarter Kotak "mobilised FCNR(B) deposits aggregating to ~₹55,344 crore and provided loans aggregating to ~₹16,110 crore" through its international branches. Strip the FCNR(B) money out and deposits grew 13%, not 23%. Strip out FCNR(B)-linked loans and the KMIL portfolio, and advances grew 19%, not 25%.
Why did the margin fall?
WCRC analysis: two effects are at work. First, about ₹55,000 crore of term money arrived in one quarter, and a large pool of fresh funds takes time to deploy at full yield. Second, RBI rules allow banks to lend to FCNR(B) depositors against a lien on their deposits. Such secured loans earn a thin spread. Kotak's release does not describe the ₹16,110 crore of international loans in detail, but loans of this kind add assets and interest income while lowering the margin ratio. The FCNR(B) money also pushed the CASA ratio down to 38.2% from 42.3%; excluding FCNR(B), it was 41.8%.
Sources and links
- wcrcint.com — https://www.wcrcint.com/wcrc-1000/company/kotak-mahindra-bank
- wcrcleaders.com — https://www.wcrcleaders.com/rbi-fcnr-swap-133bn-bank-margins
- wcrcint.com — https://www.wcrcint.com/wcrc-1000/company/hdfc-bank
- wcrcleaders.com — https://www.wcrcleaders.com/hdfc-bank-q2-fy27-deposits-profit-bagchi
- wcrcint.com — https://www.wcrcint.com/wcrc-1000/company/bajaj-finance
- mostvaluablebrands.com — https://www.mostvaluablebrands.com/megabrands/brand/mb-194
- wcrcleaders.com — https://www.wcrcleaders.com/newsroom/bfsi-sector-holds-everyones-money-has-a-people-problem/company/kotak-mahindra-bank
- wcrcleaders.com — https://www.wcrcleaders.com/rbi-first-rate-hike-since-2023-capex-festive-season
Author
WCRC Leaders